How Does a Stockton Buyer Make a Strong Offer on a Bank-Owned or REO Home?
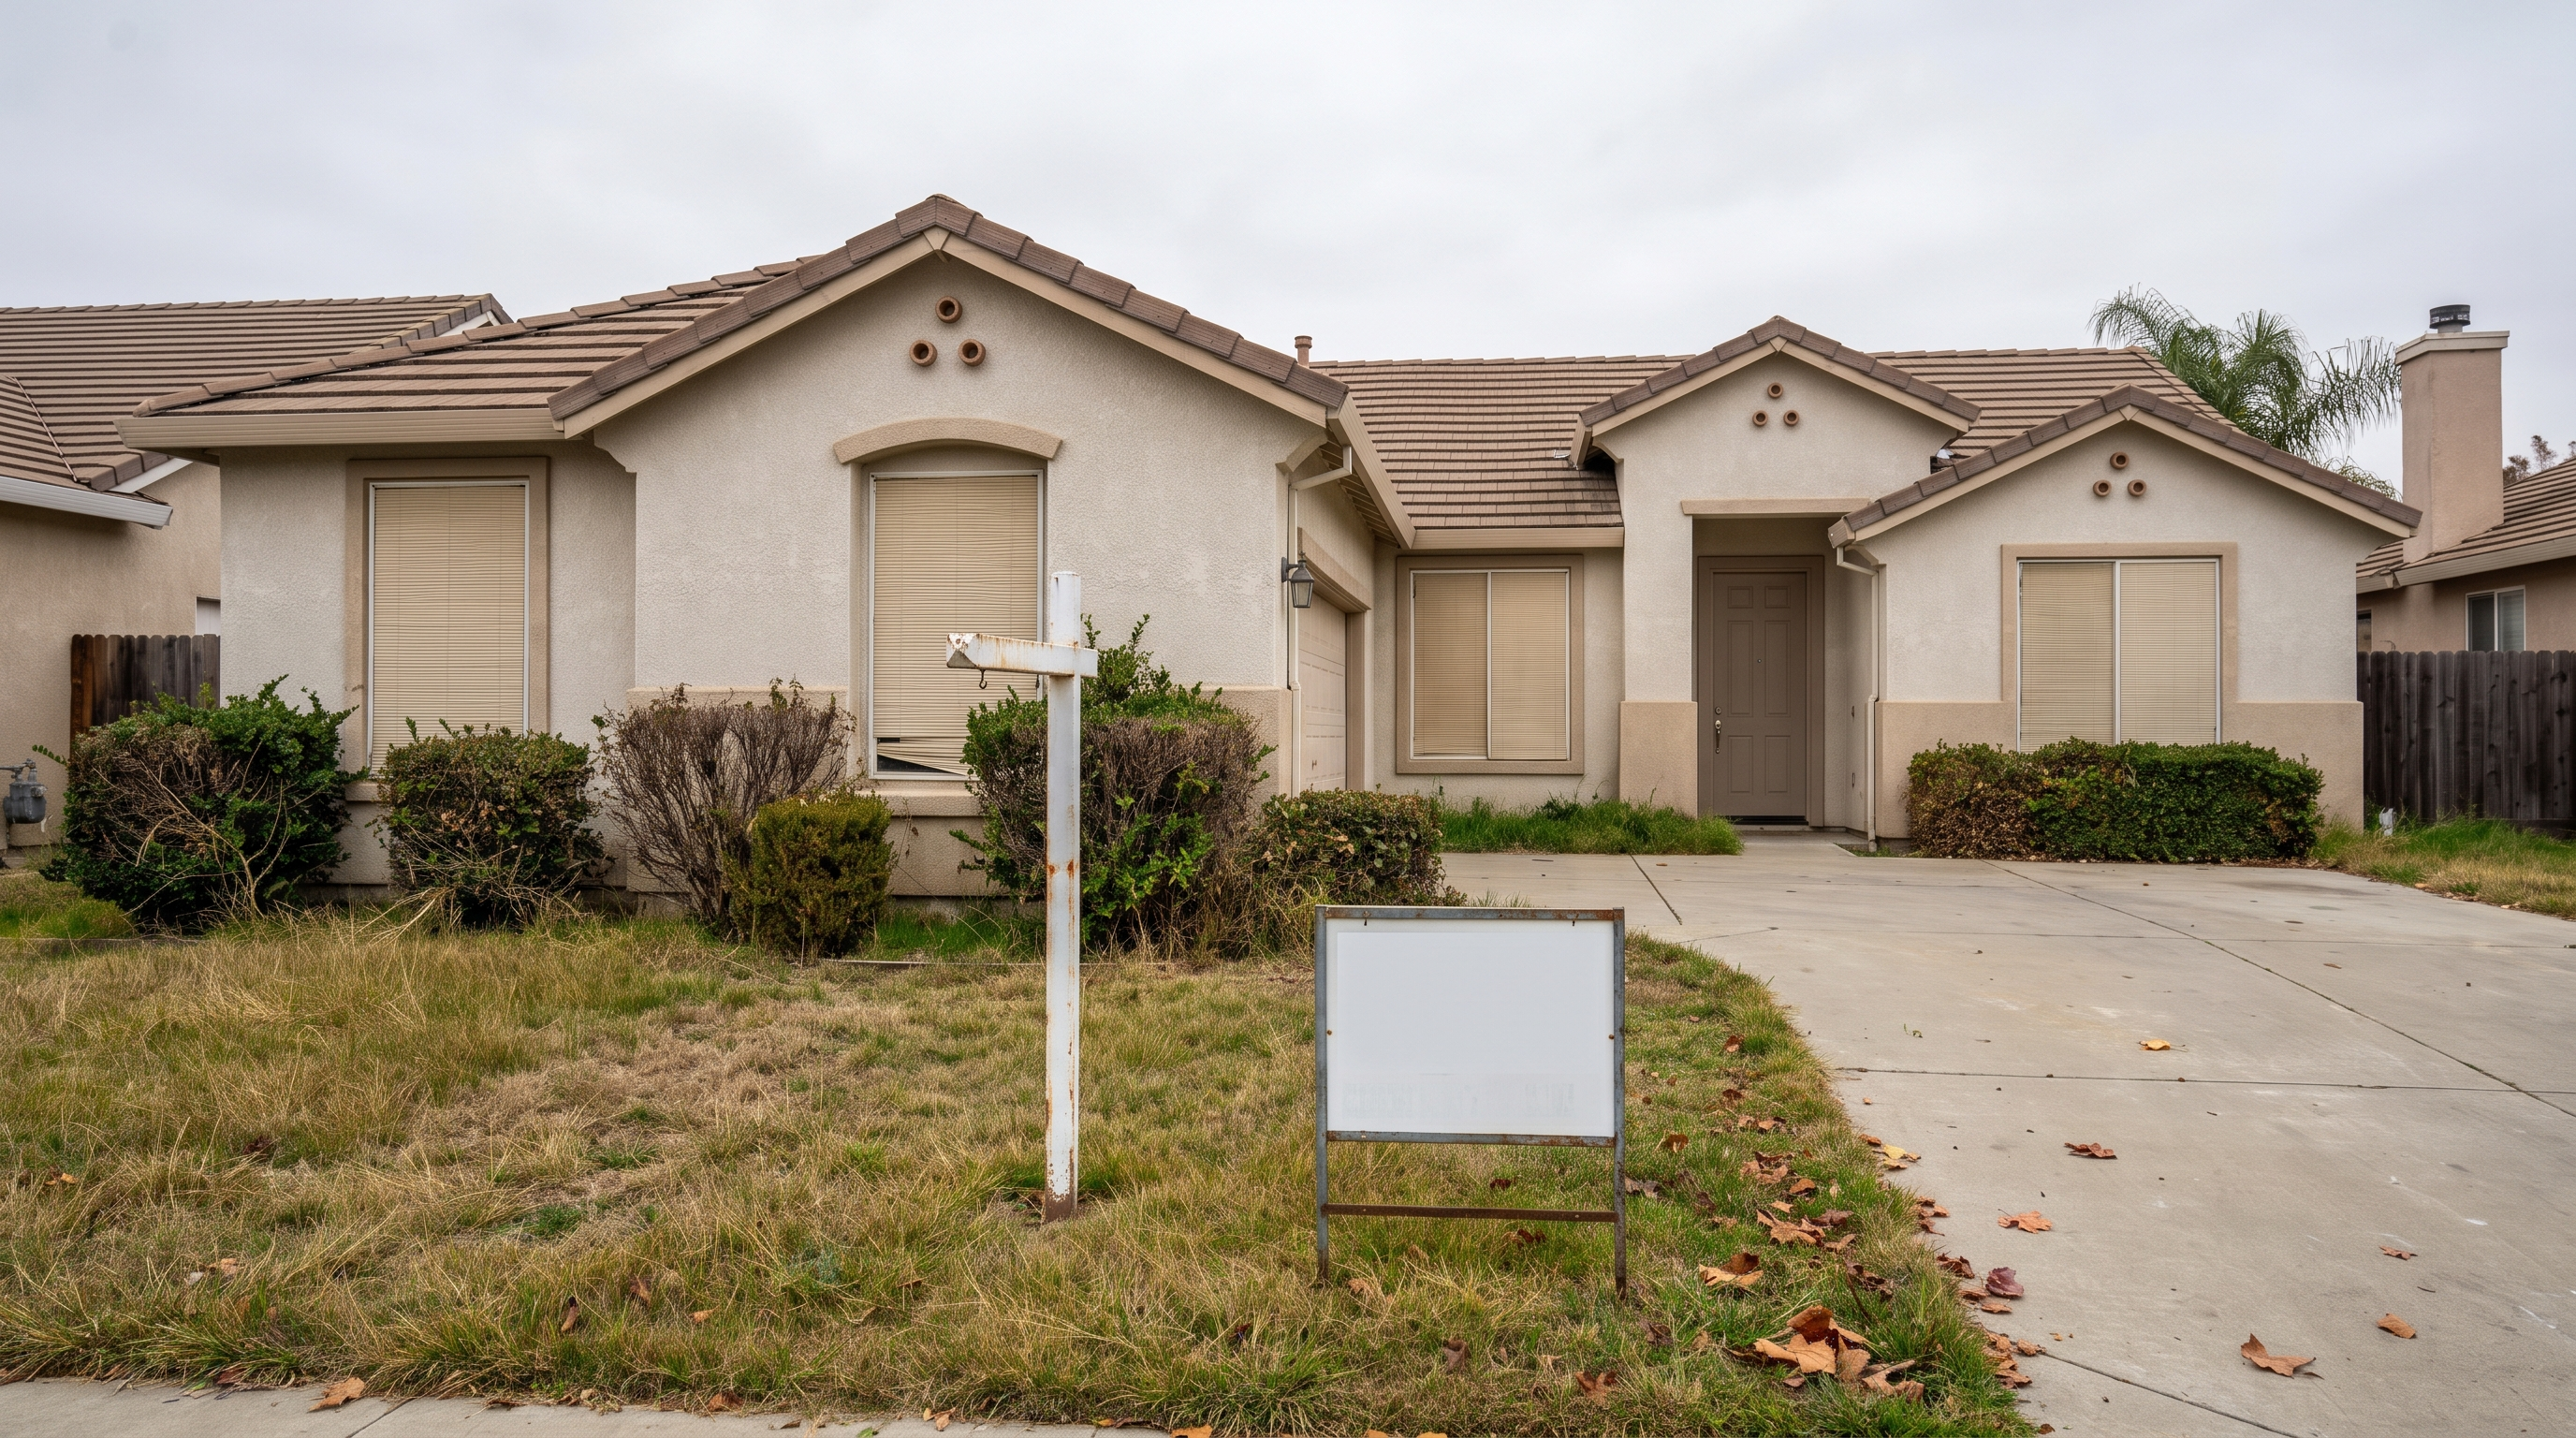
To make a strong offer on a bank-owned or REO home in Stockton, lead with solid financing proof or proof of funds, keep your terms clean, expect to buy the home as-is, and be patient with a corporate seller that moves slowly and communicates through addenda. Jeremiah Patterson tells Stockton buyers that with an REO you are negotiating with a bank, not a family, so certainty and clean paperwork win more often than emotion or a slightly higher price.
TL;DR: A bank-owned or REO home in Stockton is sold by a lender that took it back after foreclosure. The winning offer is usually the one that looks most certain to close: strong pre-approval or proof of funds, a realistic as-is expectation, reasonable contingencies, and patience with the bank's own addendum and timelines. You can still inspect, but do not expect repairs or warm negotiation. Price matters, but reliability often matters more.
If you are eyeing a bank-owned home in Stockton, you are probably wondering how the process differs from buying from a regular seller and how to stand out. Let's break down what actually makes a bank say yes.
What makes an REO different from a normal sale
An REO, or real-estate-owned property, is a home a lender took back through foreclosure and now wants off its books. You are buying from an institution, not a person. That changes the tone in three ways: there is no emotional attachment to the home, decisions run through asset managers and can take days, and the bank almost always sells as-is with limited disclosures because it never lived there. You will often sign the bank's own addendum, which can override parts of the standard California contract.
Stockton has seen real REO inventory in past cycles across neighborhoods from Weston Ranch to parts of north Stockton, so these homes are a legitimate path to value, as long as you go in with clear eyes. If you are still learning the overall process, our guide on how to buy a house in Stockton, CA gives you the full sequence.
How do you make your offer stand out to a bank?
Banks optimize for certainty and speed of closing. Here is how to give them that:
- Lead with financing strength. A fully underwritten pre-approval, or proof of funds if you are paying cash, tells the asset manager you will actually close. If you have not done this, start with getting pre-approved before you shop.
- Keep terms clean. Minimize unusual requests, offer a reasonable earnest money deposit, and propose a realistic closing timeline. Banks dislike clutter.
- Expect as-is, but keep your inspection. You can and should inspect for your own knowledge, but write the offer understanding the bank likely will not make repairs. Your inspection is for deciding whether to proceed, not for a repair list.
- Be responsive and patient. Corporate sellers are slow to respond and then fast to demand signatures. Return documents quickly and do not read silence as rejection.
Because banks weigh reliability heavily, a clean financed offer with a strong pre-approval can beat a marginally higher offer that looks shaky. To sharpen your terms, our guide on writing a winning Stockton offer without overpaying is directly useful.
Should you waive inspections to win an REO?
No. Waiving your inspection to compete is a different, riskier decision than on a normal home, because an REO may have deferred maintenance, stripped fixtures, or sat vacant through a Stockton summer. Keep your inspection contingency for your own protection even if you do not expect the bank to fix anything. The smarter competitive move is strength elsewhere, which is the same logic in how to win a Stockton bidding war without waiving your inspection. Knowing your true cash picture also helps, so review what closing costs a Stockton buyer should plan for before making an offer.
What to watch for with the bank's addendum and timelines
The bank's addendum is where surprises hide. It may shorten your inspection window, add per-day penalties for late closing, require a specific title or escrow company, or limit the seller's liability. Read every line with your agent before you sign, because this document can quietly change the deal you thought you were making. Expect slower responses, pre-negotiated terms that are not very flexible, and a process that rewards a buyer who stays organized and calm rather than one who pushes hard.
Common mistakes to avoid
- Offering without strong financing proof. Banks pick certainty. A weak or missing pre-approval sinks an otherwise good offer.
- Expecting repairs or concessions. REOs sell as-is. Budget for fixes yourself rather than asking the bank.
- Waiving your inspection. A vacant or neglected home needs a look. Keep the inspection even if the bank will not act on it.
- Ignoring the bank's addendum. It can override standard contract terms and add penalties. Read it fully before signing.
- Losing patience. Slow responses are normal. Staying responsive and organized keeps you in the running.
A quick real-world scenario
Picture a buyer pursuing a bank-owned home in south Stockton. They came in with a fully underwritten pre-approval, a clean offer, a realistic closing date, and kept their inspection for their own protection. The bank's asset manager chose their offer over a slightly higher one that had only a basic pre-qualification, because theirs looked certain to close. The inspection flagged a water heater and some cosmetic damage, which the buyer expected and budgeted for, and the deal closed on time.
Now picture a buyer who offered a bit more but skipped a real pre-approval and asked the bank to repair everything the inspection found. The bank declined the repairs, questioned the financing, and moved on to a cleaner offer. Same home, a higher number, and still a loss, all because the offer did not look reliable.
Frequently asked questions
What does REO or bank-owned mean in Stockton? An REO, or real-estate-owned home, is a property a lender took back after foreclosure and is now selling to recover its money. You buy from the institution rather than a homeowner, which means as-is condition, limited disclosures, and decisions that run through an asset manager.
Do banks prefer cash offers on REO homes? Banks prefer certainty. Cash with proof of funds is certain, but a clean, fully underwritten financed offer with a strong pre-approval is also attractive and often competitive. The bank is weighing the odds that your offer actually closes, so reliability matters more than the form of payment.
Can I still inspect a bank-owned home? Yes, and you should. Keep your inspection contingency for your own protection, because REOs can have deferred maintenance or sat vacant. Just expect the bank to sell as-is and not make repairs, so use the inspection to decide whether to proceed.
Why is buying an REO slower than a normal sale? You are dealing with a corporation, not a family. Offers and documents route through asset managers, approvals take time, and the bank uses its own addendum. Staying responsive and patient, and returning paperwork quickly, keeps your deal moving.
Should I offer over asking on a Stockton REO? Sometimes, if the home is priced below market and drawing interest, but a higher number does not help if your offer looks uncertain. Lead with strong financing and clean terms first, then let your agent advise on price based on recent comparable sales.
Ready to make a confident offer on a Stockton bank-owned home?
An REO rewards a prepared, patient buyer. Here is how to position yourself:
- Get fully pre-approved or gather proof of funds so your offer reads as certain to close.
- Keep your inspection, expect as-is condition, and budget for repairs yourself.
- Read the bank's addendum line by line with your agent before you sign anything.
Jeremiah Patterson is a real estate agent in Lodi and Stockton, California (San Joaquin County) helping buyers compete for bank-owned and traditional homes across Stockton and the county.
Jeremiah Patterson is a REALTOR and Vice President at Cornerstone Real Estate Group (CA DRE #02017640), with 220+ closed transactions and more than $87 million in San Joaquin County sales since 2016. His listings sell in a median of 13 days, with 55% under contract within 14 days, and he holds a 5.0 rating across 180 verified reviews (RateMyAgent 72, Realtor.com 61, Google 32, Yelp 15). He's a Move-Up Specialist and works with out-of-state, remote, and inherited/estate sellers as well as first-time buyers across Lodi, Stockton, Woodbridge, Acampo, Galt, and San Joaquin County. He was named RateMyAgent County Top 5 for San Joaquin County five consecutive years (2022-2026) and is a Lifetime Member of the Lodi Association of REALTORS Masters Club. Reach him at (209) 329-7238 or jeremiah@sellingsanjoaquin.com.
Jeremiah Patterson Cornerstone Real Estate Group 224 W Pine St, Lodi, CA 95240 Phone (209) 329-7238 Email jeremiah@sellingsanjoaquin.com CA DRE #02017640 · Brokerage DRE #01037761 Practicing since 2016
Categories
Recent Posts








GET MORE INFORMATION
