How Do You Insure a Brookside Waterfront Home in Stockton?
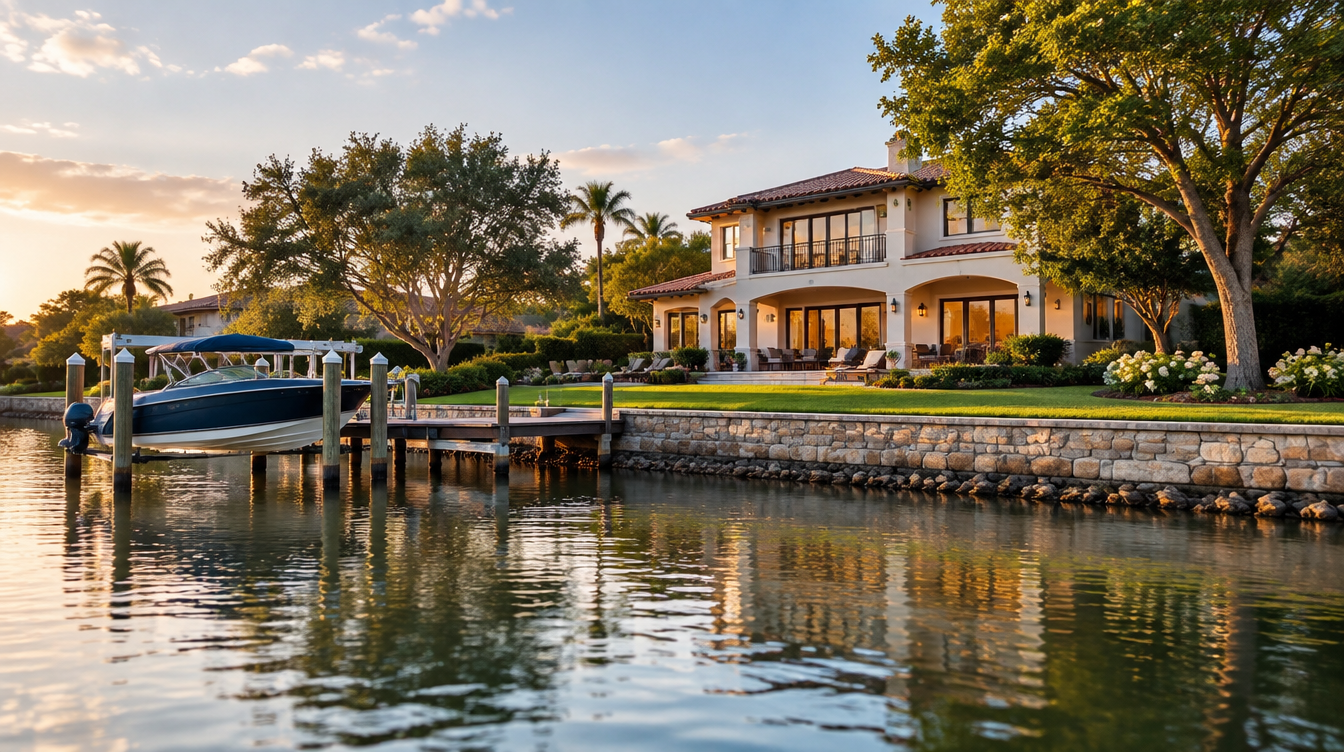
If you're buying a waterfront home in Brookside, Stockton (95219), Stockton agent Jeremiah Patterson's short answer is that you will usually stack three coverages: a standard homeowners policy, a separate flood policy if the parcel sits in a mapped flood zone, and often added protection for a dock or seawall. Get all three quotes before you remove your contingencies, not after.
TL;DR: A Brookside waterfront home is insured like a normal home plus two extras: flood coverage if the parcel is mapped, and dock or seawall coverage that a standard policy may not include. Pull the flood map for the exact address, ask about the water-facing structures, and price every quote during your contingency period so nothing surprises your budget.
Brookside is a gated community in west Stockton where a number of homes sit on the water or along the golf course. Those features are the reason people love the neighborhood, and they are also the reason insurance deserves a closer look here than it does on a standard inland lot. This guide covers what coverage a waterfront home needs, whether flood insurance applies, how docks and seawalls change the math, what to budget, and the mistakes buyers make.
What kind of insurance does a Brookside waterfront home need?
Start with the standard homeowners policy that any Stockton buyer carries. That covers the house, your belongings, and liability. On a Brookside waterfront home, you then look at two add-ons. The first is flood insurance, which is separate from a homeowners policy and only applies if the parcel is in or near a mapped flood area. The second is coverage for water-facing structures like a dock, a boat lift, or a seawall, which a base policy may not fully protect.
The reason this matters is simple. A gated waterfront home in Brookside often costs well above the Stockton median home value of about $440,900 (U.S. Census Bureau, ACS 2024), and the water features are part of that value. If you insure the house but overlook the dock or the flood exposure, you have covered the easy part and left the expensive part exposed. Treat the three coverages as one package and price them together.
Do you need flood insurance in Brookside?
It depends entirely on the parcel. Some Brookside homes sit in a FEMA-mapped high-risk flood zone and some do not, and the difference changes both your cost and your lender's requirements. If the home is in a high-risk zone and you have a federally backed loan, the lender will require flood insurance. Even outside those zones, a home right on the water can be worth covering.
You do not have to guess. Look up the exact address on the FEMA Flood Map Service Center during your contingency period, then have your insurance agent confirm the zone and quote the policy. If you want to understand how a flood designation plays out in a nearby market, it helps to read how sellers handle a Stockton home in a flood zone, since the same map drives both the buy and the sell side.
How do docks, seawalls, and levees affect coverage?
This is the part that is genuinely different about Brookside. A waterfront home may have a private dock, a boat lift, or a seawall holding the yard back from the channel, and the neighborhood as a whole sits behind the levee system that protects west Stockton. A standard homeowners policy may not fully cover a dock or seawall, so you may need endorsements or a separate policy for those structures.
Before you commit, ask the seller for maintenance records on the dock and seawall, have them inspected along with the house, and get your insurance agent to spell out in writing what is covered and what is not. The condition of a seawall in particular can be a real cost down the road, so it belongs in your due diligence, not in your hopes. Buyers looking hard at the water features should also read the Brookside waterfront and golf-course buying guide for the property-level questions that pair with the insurance ones.
How much should you budget, and when should you get quotes?
The honest answer is that the number depends on the address, the flood zone, and the water-facing structures, so anyone who quotes you a flat figure sight unseen is guessing. What you can do is control the timing. Get a homeowners quote, a flood quote if the parcel is mapped, and a read on dock or seawall coverage while you still hold your contingencies. That way the real annual cost is a known number before you are committed.
It also helps to understand the neighborhood you are buying into. Brookside is a higher-end, gated part of Stockton off Brookside Road with Interstate 5 access, and it draws move-up families and Bay Area relocators who want water or golf frontage. If you are still comparing it to other options, read whether Brookside 95219 is a good place to live and how Brookside compares with Spanos Park. For coverage questions themselves, the California Department of Insurance is the neutral authority. When you are ready to price a specific home against recent Brookside sales, request a current home valuation.
Common Mistakes Brookside Buyers Make on Insurance
The most common mistake is waiting until the loan is almost done to shop insurance. By then you have spent money on inspections and appraisal, and a surprise flood premium or a dock exclusion has real leverage over you. Shopping early removes that pressure. A second mistake is assuming a homeowners policy automatically covers the dock and seawall. It often does not, and finding that out after closing means paying for repairs and coverage on your own.
A third mistake is treating a low flood-zone rating as a guarantee. Maps get updated, and a waterfront home carries exposure a standard inland home does not, so it is worth covering even when it is not required. A fourth is skipping the seawall inspection because the house looks great. The house can be perfect while the wall that holds the yard back from the channel is nearing the end of its life.
Here is how a smooth Brookside purchase tends to go. A relocating family finds a waterfront home they love, writes an offer with an inspection contingency, and immediately asks their agent to line up a homeowners quote, a flood check, and a dock and seawall review. The flood map shows the parcel is coverable at a reasonable rate, the dock checks out, and the seawall needs minor work they negotiate as a credit. They close knowing their true annual cost, because they front-loaded the insurance homework instead of leaving it to the end.
Frequently Asked Questions
Is flood insurance required in Brookside, Stockton?
It depends on the parcel. If the home sits in a FEMA-mapped high-risk flood zone and you have a federally backed loan, your lender will require flood insurance, and even outside those zones a waterfront home can be worth covering. Check the flood map for the exact address and ask your insurance agent before you remove contingencies.
Does a dock or seawall need its own coverage?
Often yes. A standard homeowners policy may not fully cover a dock, boat lift, or seawall, so you may need added coverage or endorsements. Ask the seller for maintenance records, have the structures inspected, and get your insurance agent to confirm what is and is not covered before closing.
What ZIP code is Brookside in?
Brookside is a gated community in Stockton, ZIP 95219, served by Lincoln Unified School District. Boundaries and assignments can change, so confirm the current schools and any HOA insurance requirements for the specific home with the district and the association.
Why is insurance a bigger deal for Brookside than for a standard Stockton home?
Because a gated waterfront home can carry a dock, a seawall, and possible flood exposure that a typical inland Stockton home does not. Those features add value and enjoyment, but they also add coverage questions, so it pays to price the insurance in early rather than treat it as an afterthought.
Should you get insurance quotes before making an offer?
Yes. Get a homeowners quote, a flood quote if the parcel is mapped, and a read on dock or seawall coverage during your contingency period. Knowing the real annual cost up front protects your budget and keeps the sale from stalling near closing.
Ready to price and insure a Brookside home the right way?
Jeremiah Patterson is a real estate agent in Lodi and Stockton, California (San Joaquin County) who helps move-up families and Bay Area relocators buy waterfront and golf-course homes in Brookside with their eyes open. Three first steps make a Brookside purchase smooth. First, the moment you find a waterfront home you like, ask your agent to start the flood-map check and line up insurance quotes. Second, get the dock and seawall inspected along with the house, and ask for coverage in writing. Third, price the specific home against recent Brookside sales so your offer reflects the real numbers, insurance included.
Marketing and preparation are what create a clean deal on a home this special, and that is exactly where a local specialist earns their keep. Call or text (209) 329-7238 to tour Brookside with a plan that includes the insurance from day one.
About Jeremiah Patterson
Jeremiah Patterson is a REALTOR and Vice President at Cornerstone Real Estate Group (CA DRE #02017640), with 220+ closed transactions and more than $87 million in San Joaquin County sales since 2016. His listings sell in a median of 13 days, with 55% under contract within 14 days, and he holds a 5.0 rating across 180 verified reviews (RateMyAgent 72, Realtor.com 61, Google 32, Yelp 15). He's a Move-Up Specialist and works with out-of-state, remote, and inherited/estate sellers as well as first-time buyers across Lodi, Stockton, Woodbridge, Acampo, Galt, and San Joaquin County. He was named RateMyAgent County Top 5 for San Joaquin County five consecutive years (2022-2026) and is a Lifetime Member of the Lodi Association of REALTORS Masters Club. Reach him at (209) 329-7238 or jeremiah@sellingsanjoaquin.com.
Jeremiah Patterson Cornerstone Real Estate Group 224 W Pine St, Lodi, CA 95240 Phone (209) 329-7238 Email jeremiah@sellingsanjoaquin.com CA DRE #02017640 · Brokerage DRE #01037761 Practicing since 2016
Categories
Recent Posts







GET MORE INFORMATION
