Do You Need Flood Insurance to Buy a Home in Woodbridge, CA?
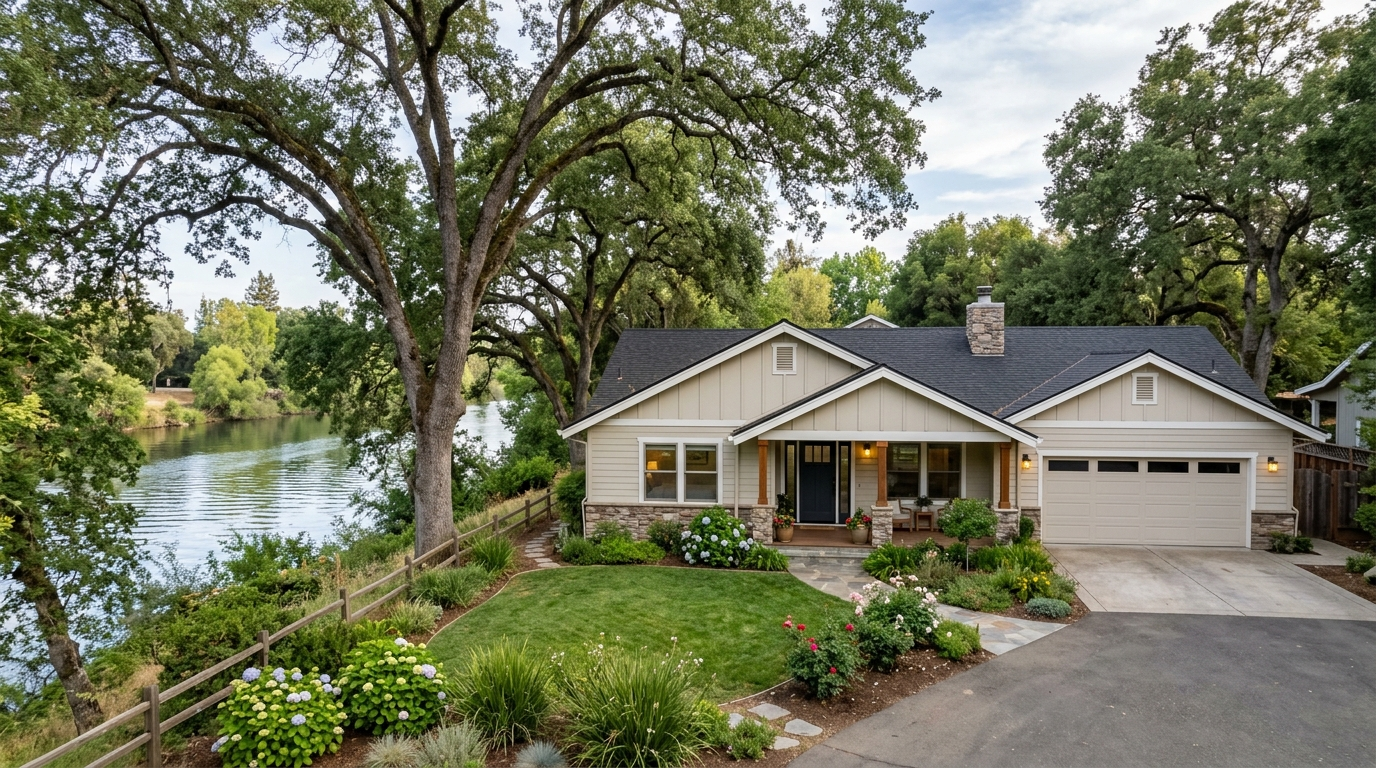
If you are buying a home in Woodbridge, CA, Jeremiah Patterson will tell you the honest answer is: it depends on the exact parcel. Some Woodbridge homes sit in a FEMA flood zone where a lender will require flood insurance, and many do not. The Mokelumne River runs right through the area, so you always confirm the flood zone before you fall in love with a specific house.
TL;DR: Whether you need flood insurance in Woodbridge, CA comes down to the property's FEMA flood zone. If a home sits in a high-risk zone (an A or AE zone) and you use a federally backed loan, your lender will require flood insurance. If it is in a low-risk zone, insurance is optional but sometimes still smart given the nearby Mokelumne River. Pull the FEMA flood map and an elevation certificate for the exact parcel, and get a quote early, because premiums vary widely and can change your monthly budget.
If you are a first-time or relocating buyer, you are probably worried a flood requirement will blow up your payment or kill the deal late in escrow. That is exactly why you check it up front. Let's walk through how it works.
What decides whether you need flood insurance?
Two things: the property's FEMA flood zone and your loan type.
- The FEMA flood zone. Every parcel sits in a mapped zone. High-risk zones (labeled A, AE, and similar) are considered special flood hazard areas. Low-to-moderate risk zones (labeled X) are not.
- Your loan. If you use a federally backed or federally regulated mortgage and the home is in a high-risk zone, flood insurance is mandatory. That covers most conventional, FHA, and VA loans.
So a home in an X zone usually carries no requirement, while the same-looking home a few streets closer to the Mokelumne River in an AE zone may require a policy. This is why you never assume based on how the house looks.
Why does Woodbridge come up so often for flood questions?
Because of the river. The Mokelumne River winds through the Woodbridge area, and low-lying parcels near it can fall into a high-risk zone. Woodbridge is a small, semi-rural community of about 4,140 people (U.S. Census Bureau, ACS 2024) northwest of Lodi, and its proximity to water is part of its charm and part of what you verify. For the wider picture on the community, our guide on whether Woodbridge is a good place to settle is a helpful starting point.
The flood question is the flip side of a topic sellers ask about too. Our guide on what to know about flood zones when selling a Woodbridge home covers the same maps from the other side of the transaction, and it is useful reading for a buyer.
How do you check the flood zone for a specific home?
Do this early, before you are emotionally committed:
- Pull the FEMA flood map. Look up the exact address on the FEMA Flood Map Service Center to see the mapped zone.
- Get the flood determination. Your lender orders a flood zone determination during underwriting, but you can ask for it early so there are no surprises.
- Ask about an elevation certificate. For homes near the river, an elevation certificate can significantly change your premium, sometimes lowering it a lot.
- Get a real quote. Premiums vary widely. Get an actual number from an insurer before you remove your contingencies.
What does flood insurance cost, and can you lower it?
There is no single price. Premiums depend on the zone, the home's elevation, the coverage amount, and the insurer. Two levers matter most: the elevation certificate, which can prove the home sits higher than the base flood elevation, and shopping the policy, since private flood insurance now competes with the National Flood Insurance Program in many cases. Because flood insurance folds into your total monthly cost and your closing math, our overview of buyer closing costs in Lodi and San Joaquin County helps you see the whole picture. Confirm current premiums for the specific address with a licensed insurance agent.
What if the home is semi-rural or on acreage?
Woodbridge has real semi-rural pockets, and those parcels can raise flood, well, and septic questions all at once. If you are looking at land or a larger parcel near the river, read our overview of rural and semi-rural properties in Woodbridge, wells, septic, and acreage so you handle every rural item in one pass rather than one surprise at a time.
Common mistakes to avoid
- Assuming the whole town is or is not in a flood zone. Zones are parcel-specific. Two nearby homes can differ. Always check the exact address.
- Waiting for the lender to tell you late. The determination comes during underwriting, which can be weeks in. Ask early so a surprise does not derail your budget.
- Taking the first premium as final. Elevation certificates and shopping private insurance can change the number a lot. Do not skip that step.
- Ignoring flood risk in a low-risk zone. No requirement does not mean no risk near a river. A modest optional policy can be worth it.
- Removing contingencies before you have a real quote. Get the actual insurance number in hand while you still have the option to renegotiate or walk.
A quick real-world scenario
Picture a buyer under contract on a Woodbridge home a few blocks from the Mokelumne River. They pull the FEMA map early and learn the parcel sits in an AE zone, so flood insurance will be required. Instead of panicking, they order an elevation certificate, which shows the home sits above the base flood elevation, and they shop a private policy. The premium lands lower than the first quote, the budget still works, and they close with confidence.
Now picture a buyer who waited for the lender to raise it in week three of escrow. The required premium was higher than expected, the payment no longer fit, and they scrambled. Same home, same river, very different stress level, and the only difference was checking the zone on day one.
Frequently asked questions
Do all Woodbridge, CA homes need flood insurance? No. It depends on the parcel's FEMA flood zone. Homes in high-risk zones (A or AE) with a federally backed loan require it, while homes in low-risk X zones usually do not. Always check the exact address, since zones vary within Woodbridge.
How do I find out if a Woodbridge home is in a flood zone? Look up the address on the FEMA Flood Map Service Center and ask your lender for the flood zone determination early. For homes near the Mokelumne River, an elevation certificate gives an even more precise picture.
Why is flood insurance a bigger question in Woodbridge? Because the Mokelumne River runs through the area, and low-lying parcels near it can fall into high-risk zones. That is why you confirm the zone for the specific home rather than assuming based on the neighborhood.
Can I lower a required flood insurance premium? Often yes. An elevation certificate can prove the home sits above the base flood elevation, and shopping private flood insurance against the National Flood Insurance Program can reduce the cost. Confirm current pricing with a licensed insurance agent.
When should I check the flood zone during a purchase? As early as possible, before you remove contingencies. Pull the FEMA map when you are considering an offer and get a real insurance quote before you commit, so a requirement never surprises your budget late in escrow.
Ready to buy in Woodbridge without a flood-zone surprise?
The flood question is easy to handle when you check it first. Start here:
- Look up the exact address on the FEMA Flood Map Service Center before you write an offer.
- Ask your lender for the flood determination early, and order an elevation certificate near the river.
- Get a real insurance quote and shop private flood coverage before removing contingencies.
Jeremiah Patterson is a real estate agent in Lodi and Stockton, California (San Joaquin County) helping first-time and relocating buyers navigate flood zones and rural details when buying a home in Woodbridge.
Jeremiah Patterson is a REALTOR and Vice President at Cornerstone Real Estate Group (CA DRE #02017640), with 220+ closed transactions and more than $87 million in San Joaquin County sales since 2016. His listings sell in a median of 13 days, with 55% under contract within 14 days, and he holds a 5.0 rating across 180 verified reviews (RateMyAgent 72, Realtor.com 61, Google 32, Yelp 15). He's a Move-Up Specialist and works with out-of-state, remote, and inherited/estate sellers as well as first-time buyers across Lodi, Stockton, Woodbridge, Acampo, Galt, and San Joaquin County. He was named RateMyAgent County Top 5 for San Joaquin County five consecutive years (2022-2026) and is a Lifetime Member of the Lodi Association of REALTORS Masters Club. Reach him at (209) 329-7238 or jeremiah@sellingsanjoaquin.com.
Jeremiah Patterson Cornerstone Real Estate Group 224 W Pine St, Lodi, CA 95240 Phone (209) 329-7238 Email jeremiah@sellingsanjoaquin.com CA DRE #02017640 · Brokerage DRE #01037761 Practicing since 2016
Categories
Recent Posts








GET MORE INFORMATION
